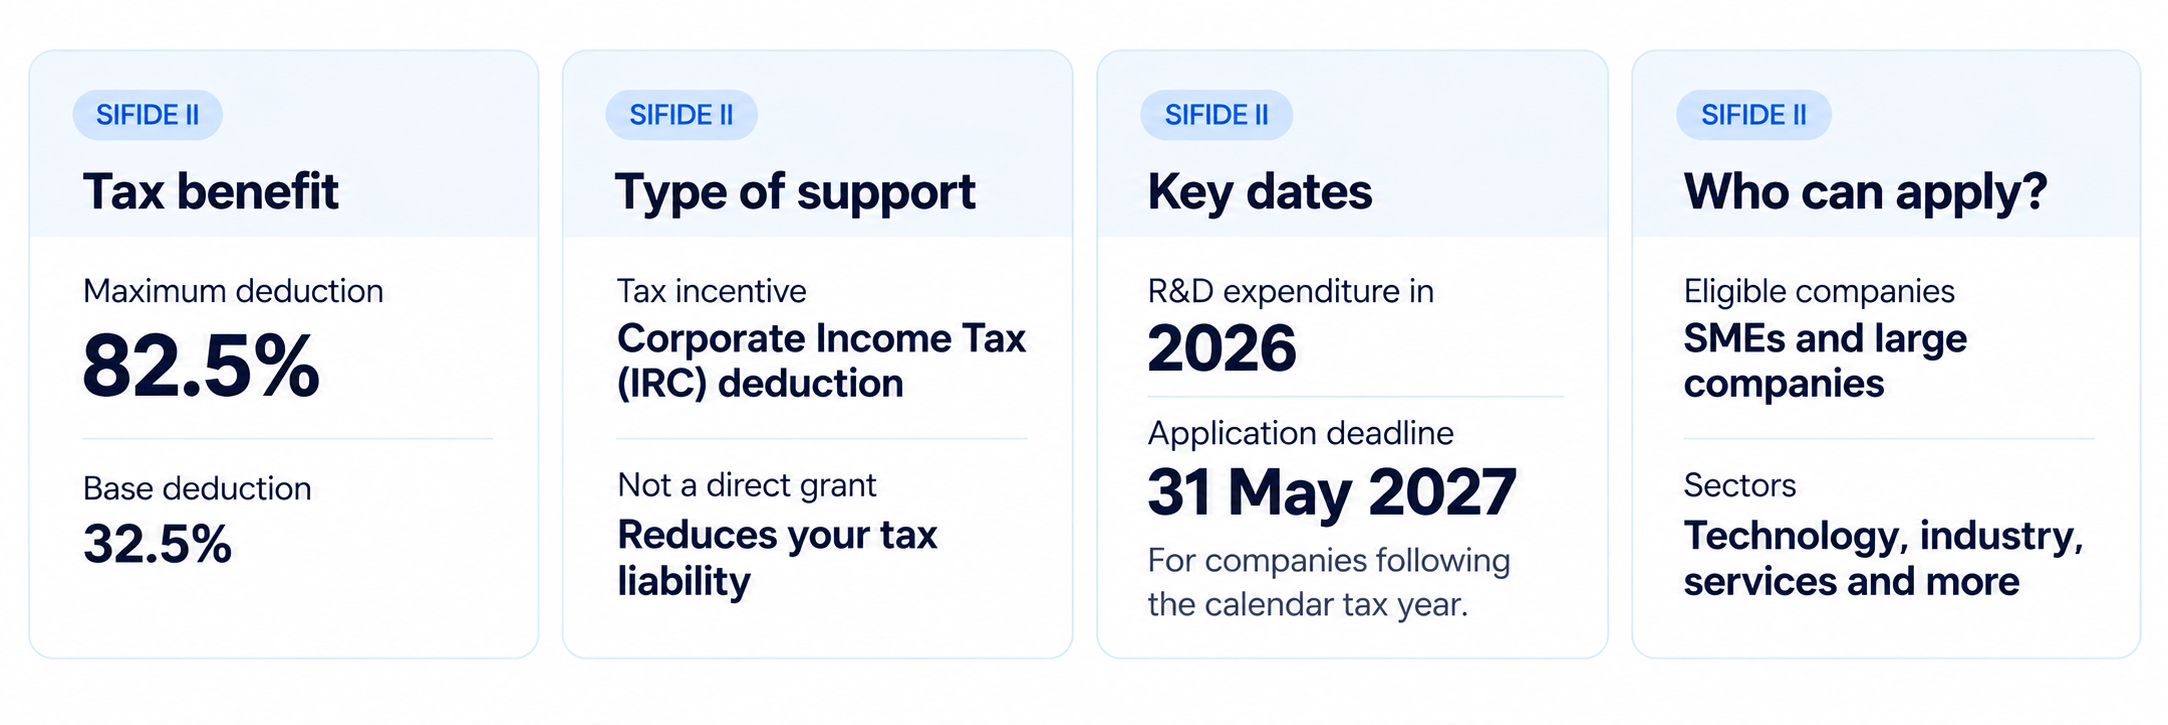
Portugal’s SIFIDE II offers companies investing in research and development (R&D) the opportunity to reduce their Corporate Income Tax (IRC), with tax deductions potentially reaching 82.5% of eligible R&D expenditure. The Sistema de Incentivos Fiscais à Investigação e Desenvolvimento Empresarial (SIFIDE II) supports business innovation by encouraging investment in new technologies, products and processes. Unlike traditional grants, the incentive provides a tax credit rather than direct financial support.
SIFIDE II has been extended to cover qualifying R&D expenditure incurred during the 2026 tax year. Companies following the calendar tax year can submit their applications until 31 May 2027.
Programme details
- Incentive programme: SIFIDE II – Tax Incentive System for Business Research and Development
- Country: Portugal
- Type of support: Corporate Income Tax (IRC) credit
- Potential tax benefit: Up to 82.5% of eligible R&D expenditure
- Base deduction rate: 32.5%
- Incremental deduction rate: 50% of the increase in eligible R&D expenditure compared with the average of the previous two tax years, subject to a €1.5 million cap
- Eligible applicants: Companies subject to Portuguese IRC that meet the relevant legal conditions
- Applicable tax periods: Extended through 2026
- Application deadline: 1 May 2027 (for calendar-year taxpayers)
- Application platform: Official SIFIDE portal
About the incentive
SIFIDE II is one of Portugal’s main tax incentives for companies investing in scientific research and technological development. The programme allows businesses to deduct a percentage of their qualifying R&D expenses from their Corporate Income Tax liability, reducing the financial impact of investing in innovation. Companies may benefit from a base deduction of 32.5%, with an additional incremental deduction potentially increasing the total benefit to 82.5%, subject to the applicable conditions.
The incentive can be particularly relevant for businesses developing new products, improving production processes or investing in technological solutions that require research and development. For example, a software company developing a new technological solution or a manufacturer working on a substantially improved production process may carry out activities that qualify under SIFIDE II. However, not every investment in technology or business improvement is considered eligible R&D.
Eligible activities and beneficiaries
SIFIDE II is available to companies subject to Portuguese Corporate Income Tax that carry out qualifying research and development activities. Both SMEs and larger companies may benefit, including foreign-owned businesses operating through eligible structures in Portugal.
The incentive can apply to different industries, including:
- Technology and software: Development of new technological solutions and qualifying software innovation.
- Manufacturing and industry: Research into new products, materials, or substantially improved production processes.
- Engineering: Development and testing of innovative technical solutions.
- Scientific research: Business projects involving new scientific or technological knowledge.
- Other business sectors: Activities involving qualifying research and technological development.
The programme is not restricted to companies whose main activity is research. Businesses in traditional sectors may also qualify when they undertake eligible R&D projects.
Main conditions to consider
To benefit from SIFIDE II, companies must meet specific legal, technical and tax requirements.
The main considerations include:
- Qualifying R&D activities: Projects must involve eligible scientific research or technological development.
- Eligible expenditure: The incentive applies only to expenses that meet the programme’s requirements.
- Tax compliance: Companies must satisfy the relevant Portuguese tax and Social Security conditions.
- Supporting information: Businesses must be able to demonstrate the nature of their R&D activities and associated expenditure.
- Application deadlines: Claims must be submitted within the applicable period through the official SIFIDE platform.
Companies receiving other public incentives should also consider possible restrictions on combining financial support for the same expenditure. Because eligibility depends on each company’s activities and circumstances, it’s important to conduct a preliminary assessment before applying.
Who can benefit?
SIFIDE II can be particularly attractive to businesses that regularly invest in product development, technological improvements or innovative processes. It may also be relevant for startups and international companies establishing research and development activities in Portugal. For companies already undertaking qualifying R&D projects, the incentive represents an opportunity to reduce their corporate tax burden and support continued investment. However, the maximum deduction does not necessarily correspond to the tax benefit a company can immediately use. The actual result depends on its eligible expenditure, previous R&D investment and corporate tax position.
Need more information?
Oporto Accounting supports businesses operating in Portugal in understanding their eligibility for tax incentives and assessing opportunities associated with research and development investment. If your company is investing in innovation, technology, or new products, SIFIDE II may offer valuable tax benefits.
To find out whether your hiring plans qualify before the 13 November deadline, please get in touch through our contact form.